Blog
White Oak Global Advisors Lawsuit: Background, Legal, Stakeholder & Financial Overview


Introduction to the white oak global advisors lawsuit
Several investors and legal professionals alongside regulatory institutions in both the US and UK have made the white oak global advisors lawsuit their principal legal focus. People use this case to explore corporate governance principles alongside fiduciary duties and financial oversight standards. The lawsuit investigates management issues along with procedural violations inside one of the most respected financial firms. The resulting legal investigations combined with substantial media coverage have taken place due to these claims.
The financial crisis has triggered widespread evaluations of the accountability systems which exist in banking institutions. The lawsuit demonstrates to stakeholders that large-scale investment management comes with significant complexities even as they claim their right to complete transparency. The lawsuit involves various stakeholders including institutional investors together with regulatory authorities who are currently exposing potential financial sector systemic problems.
This article achieves an extensive comprehension of the white oak global advisors lawsuit through systematic reviews of legal records alongside media evidence and stakeholder testimonies. Through this news article readers understand all aspects of the case controversy as it reveals its prospective impact on industry practices and regulatory reforms.
Background of the white oak global advisors lawsuit
Multiple occurrences have established the origins of the white oak global advisors lawsuit by uncovering worrying problems with their internal controls and business practices. The first reports about White Oak Global Advisors surfaced as investors identified problems with financial management and different reporting methods. Several internal audits were conducted because of mounting investor concerns until they revealed major inspection weaknesses and the possibility of management problems. The investigation obtained major evidence from financial statements in combination with internal email records along with meeting minutes.
Small groups of affected investors used both public forums and direct approaches to regulatory bodies in order to push for investigations regarding firm operations. Additional evidence uncovered showed the white oak global advisors lawsuit represented multiple industry-wide problems in finance. National and international regulators started to examine financial oversight systems while news outlets covered the story intensively because of the case’s impact. The progressive events prompted legal experts to probe into whether the company made operational choices that would benefit its investor base.
Executives faced increased examination about executive responsibility management practices as well as the effectiveness of internal control systems. The investigation provided both the timeline of lawsuit progression besides establishing essential context about the complex nature of the case. This background episode persists to affect public understanding about financial governance transparency and accountability which establishes its central importance in the complete narrative.
Legal Insights Regarding the white oak global advisors lawsuit
The legal investigation into the white oak global advisors lawsuit examines the critical aspects of the charging allegations against the backdrop of current regulatory oversight. The main legal dispute revolves around whether the firm violated its fiduciary responsibilities through improper investor fund management practices alongside unethical conduct. Several legal experts reviewed pertinent documentation while court hearings analyzed the differences between internal decisions and contractual requirements. Legal discussions have started about present legal protections versus board member awareness and involvement with related irregularities.
Legal representation from various attorneys still fights on behalf of both plaintiff groups and defendant sides through evidence evaluation that includes both financial errors and uncertain interest conflicts. Extreme witnesses appeared in multiple depositions to present evidence about how firm leadership reached their decisions through their internal conversations. The courts observe a high-risk confrontation between both parties because interpretive applications of regulatory standards and corporate governance principles drive this legal battle. The legal field follows closely documented results from previous cases that involved financial advisors and their investment firms.
Legal precedents related to this case establish boundaries for investor protection as well as clarify firm responsibility. The extensive legal details exhibited in this case highlight the intricate nature of financial litigation because the white oak global advisors lawsuit does much more than identify firm failures but it also functions to establish a legal system which will prevent future financial abuse. The legal process demonstrates an accumulated learning that will generate essential changes for financial firms subject to regulatory control in the future.
Several important parties have participated in the white oak global advisors lawsuit
The white oak global advisors lawsuit has engaged multiple essential groups of stakeholders who bring distinct views about this case. Financial advisory services face integrity challenges because several investor types including both small individual holders and large institutional entities are involved at the heart of the controversy. The alleged financial struggles of many investors stem from mismanagement and transparency issues which have damaged their investments leading them to demand responsible action from the firm. Investors who have faced adverse outcomes typically join hearings, participate with media platforms, and start class-action litigation as a means for obtaining restitution.
The US and UK regulatory bodies appear as leading voices who actively participate in this particular case. Multiple agencies analyze internal procedures of the firm to establish if financial regulations were violated. The details released through this deep examination display why regulatory control serves as essential for sustaining market security together with investor belief. A group of regulatory bodies cooperate by exchanging their expertise and evidence to achieve complete examination of every part of the lawsuit.
Performing an essential role in this situation are executives and board members who work in corporations. The decisions and oversight activities of these stakeholders face investigation due to the new allegations. Both teams of lawyers have examined business communications and decision processes while making the case more complicated. The stakeholder involvement during this legal process has demonstrated their fundamental influence on determining financial governance for the future.
Every stakeholder group that participates in seeking greater transparency and corrective actions shapes the fundamental understanding of the complete extent and influence of the white oak global advisors lawsuit.
Media Coverage and Public Reaction on the white oak global advisors lawsuit
Media outlets along with the general public reacted strongly to the white oak global advisors lawsuit which attracted broad public interest from all population segments. The lawsuit received prolonged media interest in both the US and UK jurisdictions where news outlets extensively detailed its progress. A series of critical financial and legal analysis in detailed reports helps the media present complex commercial matters to non-specialist audiences. Various news reports paired with expert legal insights along with market participant interviews have established intense public discussions about the eminent lawsuit.
Social media amplifies this story through real-time information updates and commentary that originates from people including affected individuals, legal experts, as well as financial advisors. Live Twitter discussion groups and specialized forums coupled with hashtags facilitate open discussions about developing news content through real-time interactions. Public involvement compelled authorities to display increased openness during the legal proceedings. The public response has concentrated on both holding people accountable as well as demanding reforms to prevent future such situations.
The uninterrupted media coverage functions simultaneously as a knowledge source and force that drives positive transformation. Financial institutions along with their regulators need to demonstrate full accountability according to this scrutinizing media coverage. The ongoing evolution of the white oak global advisors lawsuit has prompted media organizations to perform extensive investigative reports about the case which keeps it constantly visible to the public. The scrutinizing pressure contributes to developing a nationwide discussion about ethical finance behavior and strengthening investor protection measures across current complex markets.
Regulatory and Compliance Aspects in the white oak global advisors lawsuit
Numerous policymakers together with industry experts analyze the regulatory and compliance matters in the white oak global advisors lawsuit. The US and UK regulatory bodies carefully inspect all internal operations and risk control systems of the firm. Investor protection stands as the primary issue in terms of assessing established financial protocols and compliance measures at White Oak Global Advisors. Many experts agree that this lawsuit will uncover existing regulatory problems to emphasize the crucial requirement for regulatory reform. The regulatory boards investigate both the execution of audits within the company and their capacity to allow faulty procedures to continue.
Workplace discussions aim to enhance corporate governance measures that will protect all important parties from accountability failures. Law professionals analyze existing legal standards to determine if the current legal framework has proper capability to stop future financial fraud activities. The review process encompasses a detailed analysis of internal controls, financial reporting mechanisms, and risk mitigation strategies. The investigating procedure focuses on finding variances between conventional regulatory standards and real operational procedures observed in the firm.
This assessment will result in significant regulatory changes for the sector that operates financial institutions. Service providers would need to adopt standard compliance checks and strengthen disclosure requirements as new practice norms. The case points out how international regulatory bodies should work more closely because financial markets now operate across borders. Through this lawsuit, White Oak Global Advisors can establish rules that will enforce industry-wide standards and build transparency in the entire financial market.
Financial Impact and Investor Concerns in the white oak global advisors lawsuit
The lawsuit against White Oak Global Advisors raised several financial and investor-related issues that made the story receive extensive financial community attention. Numerous investors report substantial damage to their investments because they hold the responsible parties at White Oak Global Advisors accountable for both the mismanagement of funds and the ruined trust with their customers. Multiple specific financial investigation studies have demonstrated how several investment methods from the firm exposed market fluctuation risks. Both individual investors and large financial institutions now doubt the firm’s risk management protocols along with its decision-making processes because of recent events.
Given the lawsuit, numerous investors currently look for peace of mind regarding protection of their investments. Questions have emerged regarding firm controls to ensure proper financial reporting because some observers believe hidden actions attempted to hide financial data. The advocacy groups for investors have initiated collective demands for better disclosure, transparency, and routine auditing because they want to see ethical financial conduct reemphasized. Staff at financial institutions evaluate that these codes could establish future market modifications that would affect broader industry practices.
Market analysts presently explore what effects the lawsuit’s aftermath will have on investor confidence throughout the financial marketplace. The regulatory uncertainty brought by this lawsuit has started affecting market activities because investors now change their funding plans to adapt for new rules. The financial results and investment emotions interact intricately, thus making the White Oak Global Advisors lawsuit a landmark case in contemporary financial monitoring.
Future Outlook and Potential Reforms after the white oak global advisors lawsuit
Legal experts together with financial specialists and regulators spend considerable time speculating about the future direction of White Oak Global Advisors and its potential regulatory adjustments. Financial experts foresee the developing legal situation as a force which will drive wide-reaching changes in financial management practices. Both US and UK regulatory bodies must establish enhanced oversight regulations to stop future corporate misconduct events according to expectations. The existing compliance frameworks will be revisited, audits will become more regular, and financial reports will become more transparent as the case evolves.
All stakeholders request improved corporate guidelines that will operate alongside strengthened control protocols. Both investor trust and fiduciary duty monitoring function best when legal experts enact these reforms. Professional industry experts foresee the settlement outcome prompting standardized procedures within multinational financial corporations that will establish unified compliance procedures across global regulatory areas. Numerous experts are currently debating the possible implementation of new technologies for enhancing regulatory oversight.
Independent organizations weigh the implementation of data monitoring systems and blockchain ensuring methods to enhance the quality of corporate financial statements during auditing procedures. The White Oak Global Advisors lawsuit will continue to influence future operational practices of financial institutions because of proposed upcoming reforms. The regulatory changes born from this case will create an investment environment that promotes ethical conduct along with strict financial regulatory procedures which will remain active for successive years.
Conclusion on the white oak global advisors lawsuit
The White Oak Global Advisors lawsuit serves as a defining moment which captures the main difficulties confronting the financial sector of today. This case has exposed fundamental issues about internal management problems, missed regulations, and the required improvement of investor disclosure standards. Market confidence heavily relies on robust oversight and accountability systems in financial institutions because they provide the necessary inspections essential for maintaining market stability. The ongoing legal procedures together with reform discussions demonstrate how financial governance works across worldwide networks according to this case.
Throughout this case, investors together with regulatory bodies continue to monitor the developments due to their hope that the studied events will create better financial conditions through stronger future stability. Future court verdicts about the case will establish new standards which will push financial markets toward permanent transformations. The lessons learned from the proceedings are expected to reshape how financial institutions manage risk and uphold transparency, ensuring greater protection for investors in the future.
FAQs on Additional Aspects of the white oak global advisors lawsuit
What was the full timeline that led to starting the white oak global advisors lawsuit?
The legal process started when White Oak Global Advisors revealed inconsistencies with their financial operations and reporting protocols. The company faced investor scrutiny because of detected suspicious activities which necessitated internal audits and regulatory studies. As investigations unfolded, evidence emerged pointing to substantial mismanagement, which in turn prompted legal measures against the firm. This timeline of events underscores how investor concerns escalated into a full-blown lawsuit that is being closely monitored by regulators and the public alike.
What are the main claims forming the basis of the legal action against the company?
The legal complaints center on corporate governance violations combined with inadequate fund management and poor disclosure practices in company operations. The firm is alleged to have breached its fiduciary duties by mismanaging investor funds and failing to maintain transparent communication protocols. These deficiencies are believed to have caused significant financial harm to investors and undermined the trust placed in the firm’s management. As a result, the lawsuit asserts that proper regulatory protections were not in place to prevent these issues.
Which parties are considered primary stakeholders in this case?
The primary stakeholders include private investors, institutional entities that have experienced financial losses, regulatory organizations responsible for investor protection, and the company’s own executives and board members. Each of these groups is affected in different ways by the lawsuit, as investors seek compensation, regulators scrutinize internal controls, and corporate leaders face questions about their governance practices. The diverse range of stakeholders highlights the far-reaching implications of the case.
How does the lawsuit impact investor trust in the financial sector?
The confidence of investors is significantly shaken by major legal controversies involving reputed financial firms. The allegations have led to doubts about the effectiveness of corporate governance and risk management practices. This erosion of trust encourages calls for improved transparency, stricter oversight, and more rigorous regulatory enforcement. As market uncertainty increases, investors are compelled to demand higher accountability, which may ultimately drive industry-wide reforms.
What regulatory challenges are highlighted by the white oak global advisors lawsuit?
The case exposes deficiencies within existing regulatory frameworks, including shortcomings in internal audits, compliance enforcement, and oversight mechanisms. Regulatory bodies in both the US and UK are re-examining the processes that allowed these issues to occur, prompting discussions on the need for more stringent financial protocols. The lawsuit serves as a catalyst for potentially overhauling regulatory practices to ensure that similar lapses are prevented in the future.
What potential reforms might result from this lawsuit?
Should the legal proceedings favor stricter accountability, the outcome may drive significant regulatory reforms. Potential changes include enhanced due diligence requirements, more regular and rigorous audits, and stiffer penalties for non-compliance. These reforms are expected to strengthen the financial industry’s transparency and governance standards, ultimately protecting investors and preventing future instances of financial mismanagement.
What key lessons can investors take away from this case?
Investors learn the importance of conducting thorough due diligence on financial advisors and ensuring robust internal controls. The case emphasizes that transparency, consistent auditing, and adherence to strict regulatory compliance are crucial for protecting investments. It serves as a reminder that proactive monitoring and advocacy are essential components of safeguarding financial interests in a complex and evolving market.
Also Read:

COVID-19 is a contagious disease caused by the coronavirus SARS-CoV-2. In January 2020, the disease spread worldwide, resulting in the COVID-19 pandemic.
The symptoms of COVID‑19 can vary but often include fever,[7] fatigue, cough, breathing difficulties, loss of smell, and loss of taste.[8][9][10] Symptoms may begin one to fourteen days after exposure to the virus. At least a third of people who are infected do not develop noticeable symptoms.[11][12] Of those who develop symptoms noticeable enough to be classified as patients, most (81%) develop mild to moderate symptoms (up to mild pneumonia), while 14% develop severe symptoms (dyspnea, hypoxia, or more than 50% lung involvement on imaging), and 5% develop critical symptoms (respiratory failure, shock, or multiorgan dysfunction).[13] Older people have a higher risk of developing severe symptoms. Some complications result in death. Some people continue to experience a range of effects (long COVID) for months or years after infection, and damage to organs has been observed.[14] Multi-year studies on the long-term effects are ongoing.[15]
COVID‑19 transmission occurs when infectious particles are breathed in or come into contact with the eyes, nose, or mouth. The risk is highest when people are in close proximity, but small airborne particles containing the virus can remain suspended in the air and travel over longer distances, particularly indoors. Transmission can also occur when people touch their eyes, nose, or mouth after touching surfaces or objects that have been contaminated by the virus. People remain contagious for up to 20 days and can spread the virus even if they do not develop symptoms.[16]
Testing methods for COVID-19 to detect the virus’s nucleic acid include real-time reverse transcription polymerase chain reaction (RT‑PCR),[17][18] transcription-mediated amplification,[17][18][19] and reverse transcription loop-mediated isothermal amplification (RT‑LAMP)[17][18] from a nasopharyngeal swab.[20]
Several COVID-19 vaccines have been approved and distributed in various countries, many of which have initiated mass vaccination campaigns. Other preventive measures include physical or social distancing, quarantining, ventilation of indoor spaces, use of face masks or coverings in public, covering coughs and sneezes, hand washing, and keeping unwashed hands away from the face. While drugs have been developed to inhibit the virus, the primary treatment is still symptomatic, managing the disease through supportive care, isolation, and experimental measures.
Most Canadian homeowners set their home insurance coverage once and never revisit it. The number on the policy feels safe because it was confirmed by a professional when the coverage was arranged. The premium gets paid automatically. The policy renews each year with a modest inflation bump. Life moves on.
Then a fire damages the kitchen. Or a burst pipe floods two floors. And the claim comes back short.
Not because the insurer acted in bad faith. Not because the policy was misrepresented. But because the number the entire policy was built on was wrong from the beginning, or was right once and quietly drifted out of date.
This is more common than most homeowners realize, and it is one of the most consequential financial planning gaps in Canadian household budgets. Understanding why it happens, and what to do about it, takes about ten minutes of reading and could protect you from a five or six-figure shortfall when you need your insurance to work.
The Number You Should Be Insuring Is Not What You Think
When most homeowners think about what their property is worth, they think about the price they could sell it for. In a strong Canadian real estate market, that number has been encouraging. A home purchased in 2015 for $700,000 might sell for $1.2 million today. That feels like more than enough coverage.
The problem is that property insurance does not work on market value. It works on replacement cost, and the two figures are not the same thing, often not even close.
Understanding the difference between replacement cost vs market value is the foundation of proper insurance coverage. Market value is what a buyer would pay for your property. It includes the land, the location, the neighbourhood, and demand from buyers. It is the number that matters when you sell.
Replacement cost is what it would cost to rebuild your structure from the ground up today. It excludes the land entirely, because land does not burn down or wash away in a flood. It is calculated based on current construction costs, current labour rates, and the cost of meeting today’s building code requirements.
In high land value markets across Canada, these two figures can be dramatically different. A home in a desirable Toronto neighbourhood might sell for $1.5 million, with a large portion of that price representing expensive urban land. The actual cost to rebuild the house might be $700,000. Insuring for $1.5 million means paying premiums on $800,000 worth of coverage you could never use.
More commonly, the gap runs the other way. Homeowners set their replacement cost low, anchoring to an old estimate, and find themselves underinsured when a claim arrives.
Why Replacement Cost Estimates Go Stale
Even when a homeowner sets their coverage correctly at the start, the replacement cost figure can drift significantly out of date in a relatively short period.
Canadian construction costs have risen sharply over the past several years. Material costs including lumber, concrete, steel, copper wiring, and roofing have climbed. Skilled trades shortages have pushed labour rates higher across the country. Supply chain disruptions added additional pressure on building materials. A replacement cost estimate that was accurate in 2019 or 2020 may be significantly below the actual rebuild cost today.
Renovations compound the problem. A homeowner who spends $60,000 on a kitchen renovation, $30,000 finishing the basement, and $15,000 replacing windows and doors has added $105,000 to the cost of rebuilding their home without necessarily updating their insurance coverage to match.
Automatic annual inflation adjustments help but rarely keep pace with real construction cost increases in specific markets. A blanket 3 percent annual increase does not capture a period where skilled trade costs in your city rose 18 percent in two years.
The Co-Insurance Clause Most Homeowners Have Never Read
Hidden inside most commercial, multi-unit, and many higher-value residential policies is a provision called the co-insurance clause. If you have not read your policy documents recently, this is worth understanding.
Co-insurance clauses require you to insure your property to a minimum percentage of its full replacement cost, typically 80, 90, or 100 percent. If you fall below that percentage, the insurer applies a proportional penalty to every claim, including partial claims well below your stated policy limit.
The math is not complicated. If your home would cost $900,000 to rebuild and your policy requires you to insure to 80 percent, you are required to carry at least $720,000 in coverage. If you only carry $540,000, and you file a legitimate $200,000 claim after a kitchen fire, the insurer pays you only $150,000. The missing $50,000 comes out of your pocket, purely because the coverage was inadequate relative to the true replacement cost.
Many Canadians do not discover this clause until they are holding a reduced settlement cheque. By then, the time to fix the problem has passed.
What a Professional Insurance Appraisal Actually Does
This is where a property appraisal enters the picture in a context most homeowners associate only with buying and selling.
A professional insurance appraisal in Toronto and other Canadian markets involves a designated appraiser visiting the property, documenting its physical characteristics, assessing the quality of construction and finishes, and calculating the actual cost to rebuild the structure using current material and labour pricing. The calculation accounts for demolition and debris removal, architectural and engineering fees for the rebuild design, and the cost of meeting current building code requirements, which are often more stringent than the standards the home was originally built to.
The result is a documented, defensible replacement cost figure that your insurance broker can use to set your coverage at the right level.
This is meaningfully different from the replacement cost estimate an insurer provides using their internal calculator. Those tools apply broad assumptions to a property type and often miss property-specific features, the quality of finishes, any above-standard construction, and current local trade rates. They produce a starting point, not a property-specific answer.
A professional appraisal is built around your actual home. It produces a figure that is both more accurate and more defensible if a claim is ever disputed.
The Properties Most at Risk of Underinsurance
While any homeowner can be underinsured, certain properties are consistently underserved by generic replacement cost calculators.
Heritage and older homes. Original features including plaster walls, old-growth lumber framing, period-specific brickwork, and architectural details cost significantly more to replicate than standard contemporary construction. Generic calculators routinely underestimate rebuild costs on these properties.
Custom-built and luxury homes. High-end finishes, premium mechanical systems, custom cabinetry, and architectural features require custom analysis to cost accurately.
Homes with significant renovation history. Any property where substantial improvements have been made since the original insurance coverage was established may carry a coverage gap.
Older homes in general. Properties built to 1970s, 1980s, or 1990s standards must be rebuilt to current code if substantially damaged. The cost uplift from code compliance alone can be significant.
Condominium unit owners. Many condo owners assume their building’s insurance covers their unit comprehensively. The building policy generally covers the standard unit and common elements. Improvements you have made above the standard unit definition, upgraded finishes, custom renovations, are typically your responsibility to insure separately.
What to Do If You Are Not Sure Your Coverage Is Right
The practical path forward is straightforward.
Review your current policy for the replacement cost figure and the co-insurance requirement. Ask your insurance broker whether the figure was set using a generic calculator or a professional appraisal. Consider when the figure was last updated and what has changed since then.
If your home is older, has been renovated, contains above-standard finishes, or has not had its replacement cost professionally assessed in the past three to five years, a professional insurance appraisal is worth commissioning. The cost is modest, the process is straightforward, and the protection it provides is proportional to the claim it might someday support.
Insurance exists to make you whole when something goes wrong. For it to do that job, the number at the centre of the policy has to reflect reality, not a calculator estimate from several years ago applied to a home the insurer has never seen.
Getting that number right is not the insurer’s job. It is yours.
This article was contributed by the team at Innovative Property Solutions (IPS), a professional real estate appraisal firm providing AACI designated residential, commercial, and insurance appraisals across Toronto and the Greater Toronto Area.
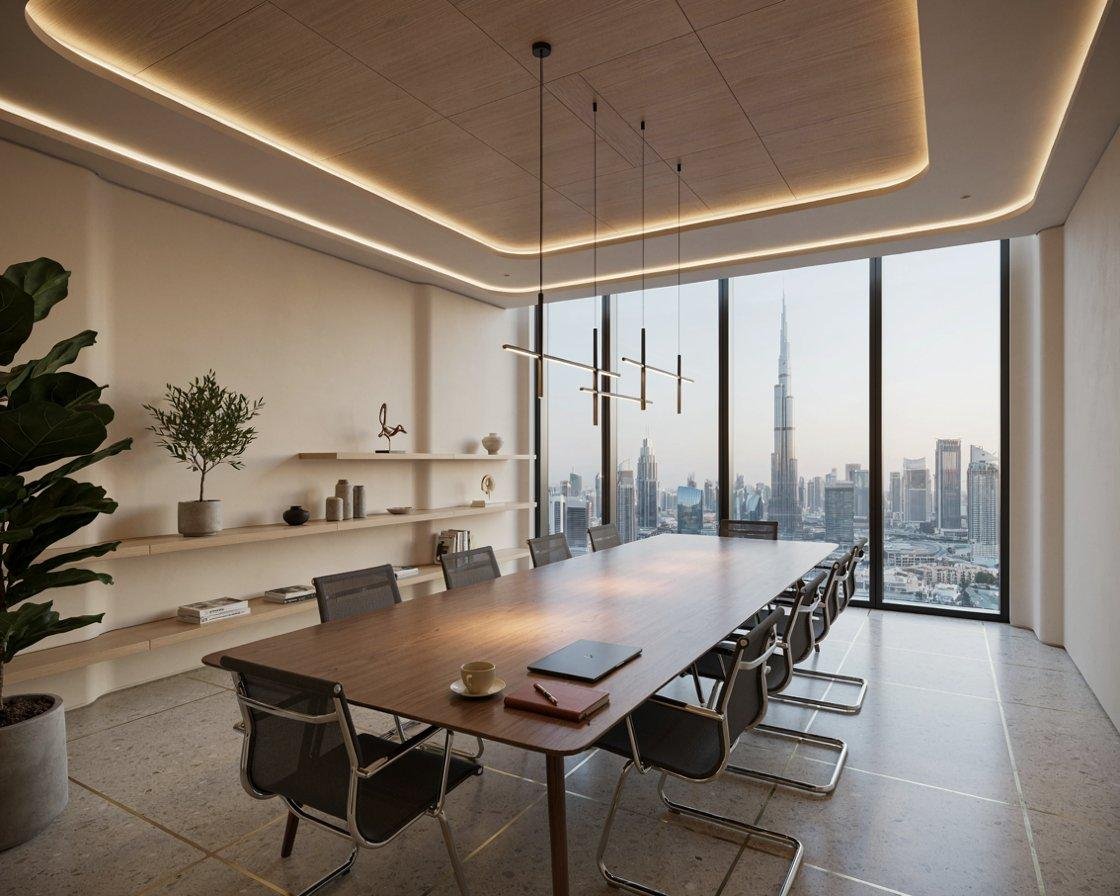
Walk into two offices that pay the same rent in Business Bay. One feels like a space someone assembled over several years — mismatched furniture, fluorescent overhead lighting, a reception desk that was clearly bought from a catalogue and placed wherever it fit. The other feels considered. The lighting shifts between zones. The reception area communicates the company’s identity before anyone says a word. The workstations are arranged so teams can collaborate when they need to and focus when they do not. Both offices cost roughly the same to run. Only one of them is working for the business.
This is the commercial interior design conversation that more Dubai businesses are starting to have — not because it is a trend, but because the evidence connecting workspace design to both employee performance and client conversion has become impossible to dismiss.
The Productivity Connection Is Not Abstract
There is a straightforward reason why companies with well-designed workspaces report lower staff turnover and higher output. People spend eight to ten hours a day in their office. The physical environment of those eight to ten hours affects every dimension of their experience: how focused they can be, how energized they feel, how comfortable their interactions are with colleagues, and fundamentally, whether the space signals that the organization they work for values them.
In Dubai specifically, the competition for skilled talent is real. A marketing agency in JLT competing for a senior hire against a tech firm in Dubai Internet City is not just competing on salary. The workspace matters in that conversation, and it matters more than most employers in the UAE currently acknowledge in their budgets.
Three specific design elements have the most direct impact on daily productivity.
Lighting. This is the single most underestimated factor in office performance and the one that makes the greatest difference per dirham spent. Standard fluorescent grid lighting produces a flat, even field that causes eye strain over long working periods and does not support the different modes of work that happen across a day. Focused task lighting at workstations, warmer ambient lighting in breakout areas, and directional lighting in meeting rooms each serve different purposes. A properly designed lighting scheme for a Dubai office supports focus during work hours, reduces fatigue, and changes the atmosphere of the space for different types of interaction. This is not expensive when designed from the outset. It becomes expensive when retrofitted after everything else is in place.
Acoustic design. Open plan offices in Dubai often fail acoustically. The combination of hard floor surfaces, glass partitioning, high ceilings, and dense workstation layouts creates an environment where ambient noise from one end of the floor reaches the other end continuously. Research consistently shows that uncontrolled ambient noise is one of the primary contributors to concentration loss and reported job dissatisfaction. Acoustic treatment does not mean adding padded walls. It means designing with materials and partition strategies that control sound distribution — acoustic ceiling panels, soft furnishing in breakout zones, glazed meeting rooms with proper door seals. These decisions happen at the design stage. They cannot be easily added after the fit out is complete.
Spatial flow. How people move through the space determines how they interact. An office where the coffee station requires walking past the CEO’s desk creates a social friction that changes how junior employees navigate their day. A meeting room positioned so that entering it requires crossing the main floor during a presentation distracts both the person entering and the people trying to focus. These are not minor inconveniences. Over time they shape the culture of the workplace in ways that are visible in staff behavior and invisible in the P&L until the correlation with turnover is noticed.
The Client Impression Is a Revenue Decision
Most commercial businesses in Dubai receive clients, partners, or suppliers at their premises at some point. The office is a physical communication of the company’s positioning, capability, and values. What clients experience from the moment they arrive at reception through to the meeting room shapes their assessment of the relationship in ways that rarely surface as explicit feedback but consistently influence decisions.
In sectors where credibility is the product — law firms, financial services, management consulting, architecture, property development — the workspace is part of the pitch. A client sitting across the table in a boardroom where the fit out matches the quality of the proposal feels differently about the engagement than a client sitting in a space where mismatched chairs and a cable-covered table send a different message entirely.
The reception area is where this matters most acutely. It is the first interior space every visitor experiences, and first impressions in physical environments form in seconds and persist. A reception desk designed and built for the specific space, with the brand properly integrated, sets a tone that everything else in the interaction builds on. A generic desk from a supplier catalogue, positioned wherever it fit in the available floor plan, sends a tone equally clearly.
This is why the companies in Dubai that invest in commercial interior design in Dubai tend to talk about it as a revenue decision, not an aesthetic one. The conversion rate in client meetings, the speed of trust-building in new relationships, and the implicit confidence signal in pitches are all affected by the physical environment in which they happen.
The Dubai Market Has Specific Dynamics
A commercial fit out or redesign in Dubai involves considerations that do not apply in most other markets, and they are worth understanding before any project begins.
The approval process is one. Any commercial interior modification that touches MEP — mechanical, electrical, or plumbing systems — or changes the layout of the space requires a Dubai Municipality building permit and a Dubai Civil Defence NOC for fire safety. From 2026, Hassantuk smart fire monitoring connection is also mandatory for all commercial premises. These are not bureaucratic obstacles to be managed around. They are legal requirements that affect the project timeline and that need to be built into the programme from day one.
The zone your office is in matters. Dubai Municipality governs most mainland commercial areas. Trakhees governs free zone areas including Palm Jumeirah, Al Furjan, and Jebel Ali. DDA governs Dubai Internet City, Media City, and Dubai Design District. Each authority has different submission portals and different drawing format requirements. A contractor who handles approvals for one zone does not automatically know the requirements of another.
Material specification matters differently here than in temperate climates. Dubai’s heat and humidity accelerate wear on surfaces that might last twenty years in a European office and last eight in an improperly specified Dubai one. Flooring choices, surface treatments, and joinery materials that are not specified for the UAE climate create visible deterioration within a few years of a fit out that looked exceptional on handover day.
Timeline realism matters. A commercial fit out in Dubai including approval processing, design sign-off, joinery fabrication, and construction typically takes 6 to 12 weeks for a standard office. Approvals run in parallel with design — not sequentially — in a well-managed project. Companies that plan for a six-week opening date without building the approval period into the programme miss that date and pay for the lease period during which the space is unoccupied.
What the Right Contractor Changes
The difference between a commercial interior project that is delivered on time, within budget, and to the specification that was agreed is almost entirely determined by the contractor chosen to execute it.
The distinction that matters most in Dubai is design-and-build versus design-only. A design-only firm produces drawings and hands them to the client. The client then manages a separate contractor to execute the work, and separately manages the approval process, or hires a third consultant for that. The design-and-build model puts all of this under one contract with one team accountable for the outcome.
For businesses in Dubai that are running the company while also managing an office fit out, the single-contract model removes a substantial coordination burden. The same team that produced the space plan is also preparing the DM permit drawings, managing the joinery fabrication, and coordinating the site. There is no gap between what was designed and what was built, because both happened with the same people.
Favoritehome is a Dubai-based design-and-build contractor working across offices, restaurants, salons, gyms, retail spaces, and hospitality projects across all Dubai zones. As an interior fit out company in Dubai that manages design, approvals, and construction under one contract, the team handles every element from the first concept to the completion certificate. The client gets one project manager, one fixed price, and one handover — rather than three separate processes running in parallel with no single point of accountability.
The Bottom Line
A well-designed commercial interior in Dubai does three things simultaneously. It supports the daily performance of the people working inside it. It communicates to every visitor something specific about the organization before anyone has spoken. And it holds its quality and value over time because the materials and the systems behind the surfaces were specified correctly for the environment.
None of those outcomes happen automatically from a fit out. They happen from intentional decisions made at the design stage, executed by a team that understands both the design objective and the construction reality of delivering it in Dubai.
The businesses in Dubai that are growing fastest are not necessarily the ones with the biggest offices. They are the ones where the workspace works — for the team, for the clients, and for the brand.
For decades, a facelift was the only real answer to sagging skin and a softening jawline. Today, that is no longer true, and the shift has been dramatic. Across York Region, more people than ever are choosing non-surgical treatments that deliver meaningful, visible tightening without a single incision, without general anaesthesia, and without the weeks of recovery a surgical procedure demands.
This is not a trend built on vanity alone. It reflects something more practical. People want results that fit into real life, a busy work schedule, family responsibilities, no time to disappear for a month of healing. Non-surgical skin tightening has stepped into that gap, and it has done so with technology genuinely capable of producing results that were once thought to require a scalpel.
Why the Shift Is Happening Now
A few factors have converged to drive this change. The technology behind non-surgical tightening has matured significantly in the last several years, reaching depths beneath the skin that were previously only accessible through surgery. At the same time, awareness has grown. People are no longer choosing between “do nothing” and “have surgery.” They understand there is a genuine middle path, one that produces real structural change rather than a temporary surface improvement.
There is also a cultural shift toward subtlety. Fewer people want a result that announces itself. Most are looking for something quieter, a version of their own face that simply looks more rested, more defined, less tired, without anyone being able to pinpoint exactly what changed. Surgical facelifts, done well, can achieve this too, but the appeal of getting there without surgery is obvious for anyone weighing the trade-offs of downtime, cost and risk.
The Two Technologies Leading the Shift
Two treatments in particular have become the names people search for when researching non-surgical alternatives to a facelift, and they work in genuinely different ways.
The first combines radiofrequency energy with precision microneedling, delivering controlled heat deep beneath the skin’s surface while simultaneously triggering the body’s own collagen-building response. This dual mechanism is what allows it to address not just fine lines, but genuine skin laxity across the face, jawline, neck and even the body, something most surface-level treatments cannot claim. Clients across Aurora, Richmond Hill and Vaughan have been turning to Morpheus8 in Aurora specifically because it reaches a depth and delivers a versatility that few non-surgical treatments can match, treating everything from early jowling to post-pregnancy skin laxity on the body.
The second approach takes a slower, more gradual path. Rather than immediately adding volume or tightening tissue on contact, it works by stimulating the body’s own collagen production over months, using a biocompatible substance the body has safely used in medical applications for decades. The result builds so gradually that friends and family often cannot identify exactly what has changed, only that someone looks well, rested, quietly refreshed. For clients dealing with broader volume loss across the face, rather than one isolated concern, Sculptra in Aurora has become a genuinely popular choice specifically because the results last years rather than months, trading a longer initial commitment for significantly less ongoing maintenance.
Who Is Actually Choosing These Treatments
The demographic pursuing non-surgical alternatives has broadened considerably. It is no longer only clients in their fifties and sixties who might once have considered a facelift. Many York Region residents in their late thirties and forties are starting treatment proactively, catching early signs of laxity before they become significant, essentially choosing maintenance over correction.
Men represent a growing share of this shift too, drawn by the lack of visible downtime and the practical, no-fuss nature of the treatment experience. For working professionals across Vaughan and Aurora, the appeal of a treatment that fits around a demanding schedule, without weeks of visible healing, has made non-surgical options an easy decision that surgery never quite was.
What a Realistic Result Actually Looks Like
It is worth being honest about what these treatments can and cannot do. Neither radiofrequency microneedling nor a collagen-stimulating treatment like Sculptra will produce the same dramatic, structural change as a surgical facelift for someone with very advanced skin laxity. What they do produce, for the right candidate, is a firmer, more lifted, more youthful version of the same face, not a different one.
This is precisely the appeal for most people exploring these options. The goal was never to look like someone else. It was to look like a well-rested version of themselves, and that is exactly what these technologies are built to deliver.
Making the Right Choice for Your Skin
With two genuinely different technologies both promising non-surgical tightening, the right choice depends entirely on individual goals, skin condition and timeline expectations. Someone wanting more immediate, versatile treatment that can also address acne scarring or body skin laxity is often better suited to radiofrequency microneedling. Someone specifically focused on gradual, long-lasting volume restoration across multiple areas of the face may find a collagen-stimulating approach the better fit.
This is not a decision to make from a search result alone. A proper in-person assessment, examining the specific skin concern and discussing realistic goals, remains the only reliable way to determine which non-surgical path actually makes sense for a given face.
Glow Med Clinic in Aurora has become one of the go-to clinics in York Region for exactly this reason, offering both technologies under one roof and, more importantly, an honest recommendation based on individual assessment rather than whichever treatment happens to be the current trend. For residents across Aurora, Richmond Hill, Vaughan and Newmarket exploring non-surgical alternatives to a facelift, a free consultation with their nurse-led team is typically the first and most useful step before committing to any treatment path.

Bebees Pink Beekeeper Suit: Comfortable, Safe & Stylish Protection
Experience the excitement of licensed casinos with Neosurf Casino Australia
Fast payouts and exciting games await at New Online Casino Canada 2026

Taylor Swift’s Producer Hints at New Album Release This Year: TS12, Reputation (Taylor’s Version), and All the Clues
麻 豆 传 媒体: A Comprehensive Insight into the Media Powerhouse